Startups
Unveiling the Discrepancy: The European Innovation Scene vs. VC Investment Trends

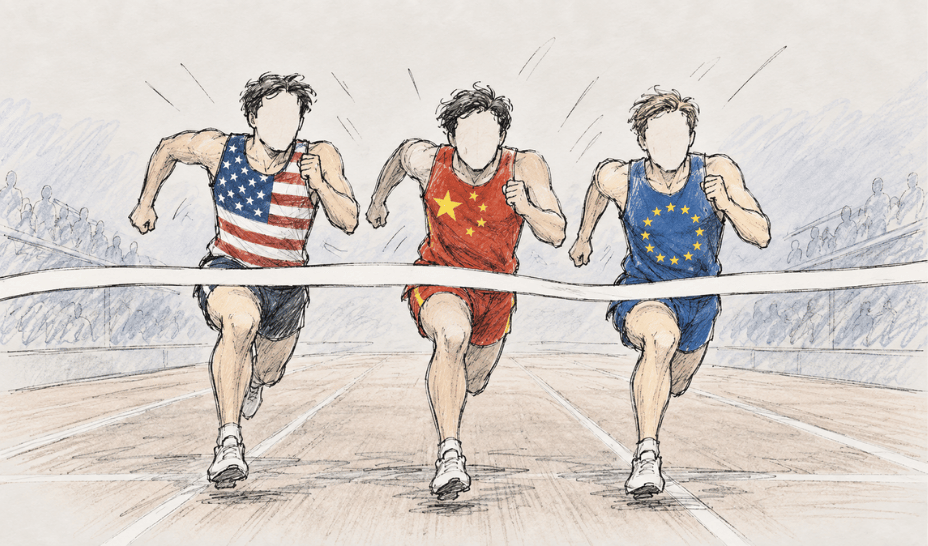
Europe may regularly be criticised for struggling to turn scientific excellence into global technology giants, but data published this week by the World Intellectual Property Organization’s (WIPO) Global Innovation Index (GII) 2026 offers a useful counterweight to that narrative.
According to the findings, 6 of the world’s 10 most innovative economies are European, giving the continent a presence at the top of the ranking that no other region matches.
Switzerland leads the GII for the 16th consecutive year, followed by Sweden in second place. The United Kingdom ranks sixth, the Netherlands seventh, Finland eighth and Denmark ninth, meaning six of the global top 10 are European. Germany follows in 11th place, France in 13th, Estonia in 17th, Austria in 18th and Ireland in 19th.
Stretch the ranking slightly further and Europe’s weight becomes even more apparent. WIPO says the region accounts for 14 of the world’s top 25 innovation economies. Norway, Belgium and Luxembourg sit immediately outside the top 20, while Italy and Spain rank 27th and 28th respectively. Twelve European economies improved their position in the 2026 edition.
WIPO Director General Daren Tang said: “AI is opening new technological frontiers across all fields in science, while government and corporate research investments reached all-time highs in 2025. Our 2026 GII report shows that a new generation of deep-science startups is translating breakthroughs into products and transforming fields such as life sciences, space, robotics and clean energy.”
The funding gap
For Europe’s founders and investors, however, the more interesting story is what happens when those rankings are placed alongside capital flows.
Despite Europe’s concentration of highly ranked innovation economies, WIPO estimates that the region accounts for just 9.9% of global venture capital deal value in 2026, based on data available for the first two quarters. Northern America accounts for 72.6%, while Asia represents 15.9%.
That contrast goes some way towards explaining one of the longstanding questions surrounding European technology: the continent clearly possesses many of the ingredients required for innovation, but converting research, talent and infrastructure into companies operating at global scale remains a more complicated task.
WIPO makes the point explicitly. It describes Europe’s central challenge as turning its research and industrial strengths into fast-growing firms, scaleup finance and productivity growth. In other words, Europe’s position in the ranking suggests there is no shortage of raw material. The challenge is increasingly what happens to an idea after it leaves the laboratory, university or early-stage startup.
But it also outlines that venture capital has rebounded, although the headline numbers hide a rapidly concentrating market. Global VC deal value jumped around 28% in 2025 to €454 billion ($510 billion), its strongest increase since 2021. AI accounted for 53% of that value and an extraordinary 77% during the first half of 2026. At the same time, the number of deals fell by 1.4%, marking a fourth consecutive annual decline.
Capital is still moving
Against that backdrop, EU-Startups’ 2026 coverage suggests that European venture firms are still raising substantial pools of capital, even if those sums remain small relative to global deal value.
Across the fund launches, first closes, final closes and institutional commitments covered so far this year, the headline amounts add up to roughly €9.6 billion, with several individual vehicles reaching significant scale.
Barcelona-based Kembara announced a €750 million first close for its planned €1 billion DeepTech fund, while DTCP and the Earlybird-AVP-backed E2D vehicle each raised or launched €500 million strategies focused on defence, resilience and dual-use technologies. QuantumLight raised €432 million for its second fund, Earlybird closed €360 million for Fund VIII, Mouro Capital reached a roughly €344 million first close, and Seedcamp raised €279 million across two vehicles.
EU-Startups’ own July snapshot of the 10 largest European VC funds announced in 2026 put their combined value at around €3.29 billion. The pattern is notable: much of this capital is being directed towards DeepTech, AI, defence, climate, life sciences and university-linked innovation, precisely the areas where Europe already shows strong research and scientific capacity.
Deep science gathers pace
The report’s special focus on deep science maps more than 30,000 startups created since 2000 across fields including semiconductors, robotics, quantum computing, life sciences, space, energy and advanced materials. That is 9.5 times the number recorded in 2010, while deep science companies accounted for a 15-year high of 16% of all venture-backed startups in 2025.
Together, these businesses are valued at €6.7 trillion ($7.6 trillion), an increase of 23% from 2024. Deep science startups attracted €108 billion ($122 billion) in venture capital during 2025 and, once rounds worth more than €222 million ($250 million) are excluded, the category accounted for 36.5% of global VC funding – close to twice its share a decade earlier.
Europe has a substantial position within that emerging landscape. The United Kingdom alone is home to 2,133 deep science startups, the third-largest total worldwide after the United States with 12,752 and China with 3,466. Perhaps more surprising is Estonia: its number of deep science startups grew by 313% between 2020 and 2025, the fastest rate recorded among the economies covered by WIPO.
The strength of Europe’s research ecosystem is also visible at city and university level. Cambridge in the United Kingdom is the world’s second most innovation-intensive cluster relative to population, while Oxford places fifth. Eindhoven ranks eighth and Helsinki ninth, and five European Union clusters appear among the global top 15 for innovation intensity.
On a broader measure of innovation clusters, Germany has seven among the global top 100, putting it behind only China, with 25, and the United States, with 20. The United Kingdom has four. London is Europe’s highest-ranked major cluster at eighth globally, followed by Paris in 11th.
The scale-up test
Europe’s showing in the 2026 index therefore tells two stories at once. Its research institutions, skilled workforces, infrastructure and established innovation ecosystems continue to put European economies disproportionately close to the top of the global table.
Switzerland, Sweden and their European neighbours demonstrate that the continent remains one of the world’s most fertile environments for creating new knowledge.
The numbers on venture funding show where the gap remains.
With 11 European nations ranking in the top 20 globally for innovation, it is clear that the region has immense potential in the tech industry. However, despite this impressive performance, less than one-tenth of the estimated global venture capital deal value is currently flowing into Europe as of 2026. This discrepancy highlights a crucial challenge that needs to be addressed moving forward.
The key to unlocking Europe’s full potential in the tech sector is not just about generating more inventions. It is about creating an environment where companies emerging from Europe’s research labs, universities, and startup communities have access to the necessary capital and resources to scale and become the next wave of global technology leaders.
In order to foster the growth of these innovative companies, it is essential to ensure that they have the financial backing and supportive conditions needed to thrive. By investing in these emerging tech startups and providing them with the right ecosystem for development, Europe can position itself as a major player in the global tech landscape.
By focusing on supporting and nurturing these budding tech companies, Europe can harness its innovative capabilities and propel the region to new heights in the tech industry. It is not just about creating more inventions, but about empowering these inventions to reach their full potential and make a lasting impact on the world stage.







Potential BMW Models Facing the Chopping Block

The Witcher 3: Echoes of History

Unveiling the Discrepancy: The European Innovation Scene vs. VC Investment Trends

Pokémon Go: Robbing iPhones and Winning Big at the Casino

The Truth about the OnePlus 5T – REAL Review.

Malevolent Warlock Harnesses SharePoint Vulnerabilities to Disable Security Measures and Unleash Ransomware

Resident Evil: Timelines Collide – A Mysterious Crossover Adventure

Tech Titan’s Body Scan Revolution Hits US Shores

GrayKey Tool Outsmarts iPhone’s 72-Hour Inactivity Reboot

EU Takes Action Against Instagram and Facebook for Violating Illegal Content Rules

Warning: Facebook Creators Face Monetization Loss for Stealing and Reposting Videos

Facebook’s New Look: A Blend of Instagram’s Style

Facebook Compliance: ICE-tracking Page Removed After US Government Intervention

Facebook and Instagram to Reduce Personalized Ads for European Users

InstaDub: Meta’s AI Translation Tool for Instagram Videos

Reclaim Your Account: Facebook and Instagram Launch New Hub for Account Recovery

Meta discontinues Messenger apps for Windows and macOS

Breaking Updates: Meta Connect 2025 Unveils Latest Developments
The Truth about the OnePlus 5T – REAL Review.

Concept Smartphones that are better than Real Smartphones

Samsung Galaxy SII Unboxing!

The SECRET to Maximise Smartphone Battery Life?

We Designed the Ultimate Gaming Smartphone of 2018!

Using the Cheapest Smartphone in the World.

Samsung Galaxy S9+ Unboxing! (Clone)

Unboxing the First Ever Samsung Galaxy S!!

Huawei P Smart – Huawei’s new Killer Budget Smartphone!
-
 Facebook11 months ago
EU Takes Action Against Instagram and Facebook for Violating Illegal Content Rules
-
 Facebook12 months ago
Warning: Facebook Creators Face Monetization Loss for Stealing and Reposting Videos
-
 Facebook10 months ago
Facebook’s New Look: A Blend of Instagram’s Style
-
 Facebook12 months ago
Facebook Compliance: ICE-tracking Page Removed After US Government Intervention
-
 Facebook10 months ago
Facebook and Instagram to Reduce Personalized Ads for European Users
-
 Facebook12 months ago
InstaDub: Meta’s AI Translation Tool for Instagram Videos
-
 Facebook10 months ago
Reclaim Your Account: Facebook and Instagram Launch New Hub for Account Recovery
-
 Apple12 months ago
Meta discontinues Messenger apps for Windows and macOS